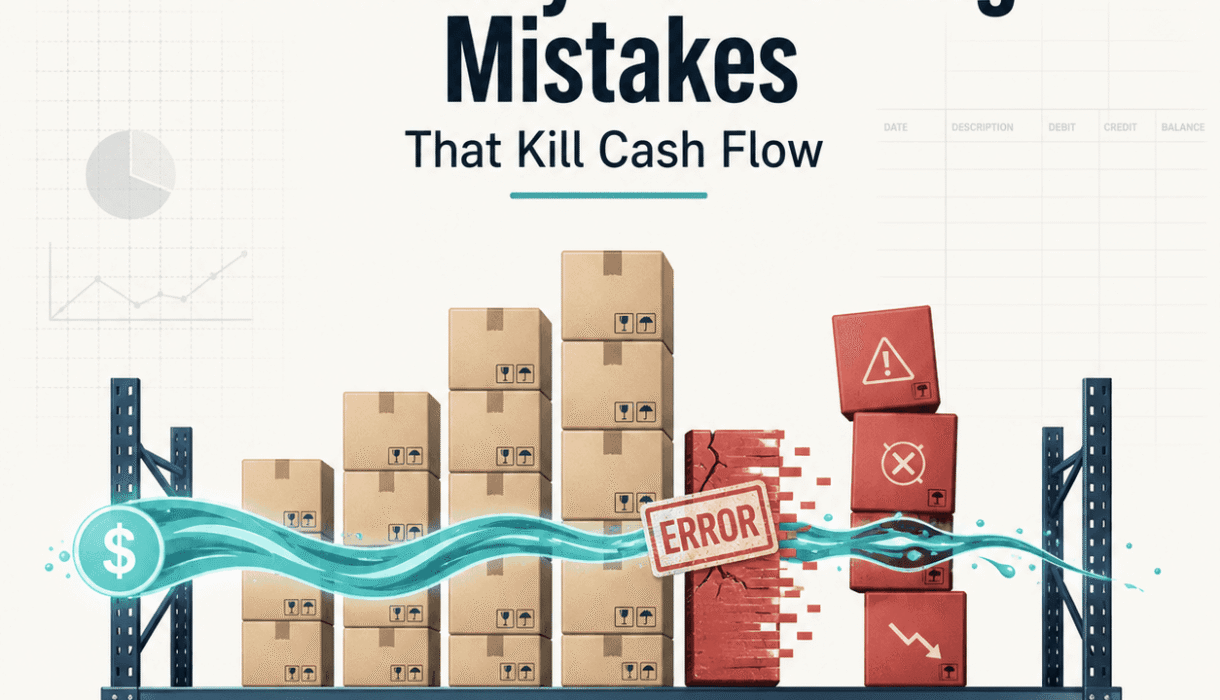

Cash flow problems usually look like this.
You check your bank account, you check your sales, and you think, we are busy. We are shipping orders. The team is working. The phone is ringing. So why does it feel like we are always behind.
A lot of the time, it is not sales. It is not even expenses in the obvious way. It is inventory accounting.
Inventory is sneaky. It can make your profit look higher than it is, or lower than it should be. It can hide theft, hide purchasing mistakes, and make you think a product line is “crushing it” when it is quietly draining cash every single month.
So let’s talk about the inventory accounting mistakes that actually kill cash flow. Not theory. Not textbook stuff. Real things we see in bookkeeping cleanups, especially in QuickBooks Online.
If you want someone to look at your setup and point out what is off, Smart Bookkeeping Partner offers a free QuickBooks health check here: https://smartbookkeepingpartner.com/
And yes, it is basically what it sounds like. What is reconciled, what is messy, what is missing, what needs cleanup. Then you get a walkthrough.

1. Not tying inventory movement to real purchasing and selling
This one is the root of everything.
If your system is showing inventory going up and down, but it is not directly connected to what you actually buy and what you actually sell, you end up with “phantom inventory” and distorted financials.
Common ways this happens:
- Purchases are coded to an expense account like Supplies or Cost of Goods Sold instead of Inventory Asset
- Sales are recorded as income, but the cost side is not being relieved properly
- Inventory adjustments get posted randomly to “fix” quantities without understanding the financial impact
Cash flow impact: You reorder too early, or too late. You think you have cash because profit looks fine. Then you get hit with a big restock, and suddenly the bank account tells the truth.
What to do instead:
- Purchases for resale should generally go to Inventory Asset (until sold)
- Sales should reduce inventory and book COGS properly
- Adjustments should be rare, documented, and posted to the right accounts
If you are using QuickBooks, this is where a lot of businesses accidentally break the link without realizing it.
2. Mixing cash basis thinking with accrual inventory accounting
Even if you prefer looking at cash basis reports for taxes, inventory does not behave like normal expenses.
Inventory is an asset until it is sold.
So if you buy $80,000 of product in March and sell only $25,000 worth of it by month end, your March Profit and Loss should not show $80,000 of COGS. It should show the cost of what you sold. The rest sits on the balance sheet as inventory.
Where things go wrong is when owners look at the bank balance and mentally treat inventory buys as “COGS,” then compare it to sales.
That makes you feel like margins are terrible when maybe they are not. Or it makes you feel like margins are great because COGS looks low, but you are actually sitting on a pile of inventory you cannot move.
Cash flow impact: You make decisions based on the wrong story. You stock up more because margins “look good.” Or you cut marketing because margins “look bad.” Meanwhile, cash is draining either way.
3. Ignoring landed cost (and pretending freight does not exist)
If you import, ship pallets, pay receiving fees, pay duties, or even just pay meaningful inbound freight, landed cost matters.
And if it is not being tracked correctly, your margins are basically fiction.
Example:
- Unit cost from vendor: $12
- Freight and inbound shipping per unit: $2
- Duties and fees per unit: $1 Real cost: $15
If your books keep recording cost as $12, your gross profit looks better than reality. You price products too low, you run discounts that are not actually profitable, and you scale something that is quietly losing money.
Cash flow impact: You “grow” yourself broke. Sales increase, but every sale brings less cash than you think.
Basic approach:
- Decide what you will include in landed cost (freight, duties, prep fees, etc.)
- Allocate those costs to inventory, not just an expense bucket
- Keep it consistent month to month
QuickBooks can do some of this, but many businesses need a process outside of it, then a clean monthly entry to reflect the true cost.
4. Not doing cycle counts, ever
If you do not count inventory, your inventory number becomes a guess. A guess that gets worse each month.
Reasons inventory gets off:
- Damage and spoilage
- Returns not processed correctly
- Mis-picks and shipping errors
- Theft
- Unit of measure issues (cases vs each)
- Bills entered with wrong quantities
- Sales orders fulfilled incorrectly
When businesses finally do a physical count once a year, they often discover a massive adjustment. And that adjustment hits the Profit and Loss.
Cash flow impact: You are flying blind, so you either overbuy or stock out. Both are cash flow killers. Overbuying ties up cash. Stockouts create chaos, rush shipping, missed sales, and unhappy customers.
Do this instead:
- Start with cycle counts of your top sellers and highest dollar SKUs
- Count consistently (weekly or monthly cadence)
- Track shrinkage as a KPI, not as a shameful surprise
5. Using the wrong inventory valuation method (or switching accidentally)
This gets technical fast, but it matters.
If your valuation method does not match your reality, your cost of goods sold will swing in ways that do not make sense.
Common valuation methods:
- FIFO (first in, first out)
- Weighted average
- Specific identification (less common unless you track unique items)
The bigger issue is not which method you pick. It is when your systems and processes create accidental changes.
For example:
- You change how you enter bills
- You turn on inventory tracking mid-year
- You migrate from one platform to another and the item costs come over wrong
- You start using bundles, assemblies, or manufacturing, but still “wing” the costs
Cash flow impact: Unstable gross margin leads to bad decisions. Also, incorrect inventory on the balance sheet affects borrowing, investor conversations, tax planning, and pretty much every “should we do this?” decision.
If you are not sure your inventory valuation can be trusted, that is exactly the kind of thing that shows up in a QuickBooks health check.
6. Bundles and kits that are not costed correctly
This is a big one in ecommerce.
You sell a bundle. A kit. A multi-pack. A “starter set.”
But your bookkeeping sees it like a single item with a random cost you guessed three months ago.
If the kit is not linked to the components and the component costs are not updating, then COGS is wrong and inventory levels are wrong.
Cash flow impact: Bundles often get priced aggressively. If you are not tracking component cost changes, the bundle can drift from profitable to barely break-even. And you will not notice until cash gets tight.
Solution options:
- Use proper bundling features in your inventory system
- Use a connector app that pushes accurate COGS into accounting
- Or create a consistent month-end adjustment process (not perfect, but better than guessing)
7. Treating inventory purchases as “just expenses” because it is simpler
This one is understandable. It really is.
Owners are busy. They want the books done. So someone says, “Let’s just expense it all to COGS. Close enough.”
Except it is not close enough once inventory is a real part of cash flow.
If you expense purchases immediately:
- Your monthly profit becomes timing-based noise
- Your balance sheet is useless
- You cannot forecast cash needs properly
- You cannot trust margins by product line
Cash flow impact: You can be profitable and still run out of cash because you are buying too much inventory. Or you can be unprofitable and not realize it because the timing makes the month look fine.
The whole point of clean inventory accounting is to stop guessing.

8. Reconciling bank and credit cards, but not reconciling inventory
A lot of business owners hear “reconciled books” and think that means bank reconciliations only.
Bank reconciliation is necessary. But with inventory businesses, it is not sufficient.
You also need:
- Inventory subledger reconciliation (does your item system match your accounting system?)
- COGS reasonableness checks (does margin make sense based on pricing and known costs?)
- Balance sheet review (inventory asset trending logically, not flatlining or spiking with no reason)
- Clearing account reconciliation if you use one for inventory in transit
Cash flow impact: If your inventory numbers are wrong, forecasting cash is basically a coin flip. Especially around restock cycles.
This is part of what Smart Bookkeeping Partner focuses on. Clean, reconciled books first. Then decision-ready data. Because otherwise the “advisory” is just vibes.
9. Returns and refunds not handled with the right inventory flow
Returns are messy. And a lot of systems record them in a way that looks fine on the surface, but breaks inventory.
A few common mistakes:
- Refunding a customer but not bringing inventory back in (or bringing it back in incorrectly)
- Returning to inventory items that are damaged and should be written off
- Recording returns as a flat discount instead of reversing revenue properly
- Not capturing return shipping or restocking costs, so you understate the real cost of returns
Cash flow impact: You think you have more sellable stock than you really do. You also underestimate how much returns are costing you. Which leads to overbuying, underpricing, or both.
10. Not forecasting inventory cash needs (and then acting surprised)
Inventory businesses do not just “spend money.” They spend money in chunks.
You place a PO. You pay a deposit. You pay the balance. You pay freight. You pay storage. You pay prep. Then you wait to earn it back.
If you are not mapping that timing, your cash flow will always feel like whiplash.
What to do:
- Build a simple 13-week cash flow forecast
- Layer in expected inventory purchases by date
- Track lead times and reorder points
- Watch cash conversion cycle (how long cash stays tied up before returning)
This is where CFO advisory work starts to matter. Bookkeeping tells you what happened. Forecasting tells you what is about to happen.
Smart Bookkeeping Partner does this kind of cash flow monitoring and KPI tracking as part of advisory support, once the books are clean enough to trust.
11. QuickBooks inventory turned on, but not maintained
QuickBooks inventory can work for some businesses. But it is not “set it and forget it.”
When it goes wrong, it goes wrong quietly.
Typical issues:
- Negative inventory because sales were entered before bills
- Items created inconsistently (same product, multiple item records)
- Costs overwritten manually and never corrected
- Adjustments made without documenting why
- Old items never inactivated, reports become noise
Cash flow impact: You lose confidence in reports, so you stop using them. Then you go back to gut feel. And gut feel is expensive.
If you are already in QuickBooks and not sure if your inventory is healthy, a QuickBooks health check is a fast way to identify the big red flags: https://smartbookkeepingpartner.com/
12. Payroll bloat in fulfillment and operations, without tracking the true unit economics
Inventory accounting is not only about the products. It is also about the people required to handle those products.
If your payroll is growing in receiving, picking, packing, and customer support, but you are not tracking labor cost per order (or per unit), cash flow can deteriorate even while sales grow.
Two things help here:
- Clean department or class tracking for payroll costs
- Better payroll reporting and simpler processes so you can actually see what is happening
If you are looking for a payroll platform that plays nicely with bookkeeping, Gusto is a common choice.
Smart Bookkeeping Partner has a Gusto referral promo for new clients. If you sign up using this referral link, after your first paid bill you will receive $200 worth of gift cards:
https://gusto.com/r/everylanne4b19bb6
A simple gut check (if you only do one thing this week)
Here are a few quick questions that usually reveal whether inventory accounting is hurting cash flow:
- Does your inventory balance make sense relative to how much you sell in a month?
- Do your gross margins swing wildly for no clear reason?
- Do you regularly stock out of “best sellers” while sitting on slow movers?
- When you do a physical count, is it always a painful surprise?
- Do you trust your COGS number, like actually trust it?
If the answer is no to any of these, it is probably time for a cleanup.
And this is the part where I will say it plainly.
If you want a second set of eyes on your QuickBooks and inventory accounting setup, Smart Bookkeeping Partner offers a free QuickBooks health check and walkthrough: https://smartbookkeepingpartner.com/
Or call 985-401-1210 if you prefer to talk it through.
Because once inventory is clean, cash flow becomes a lot less mysterious. Still not perfect. Still business. But at least you are not making decisions based on numbers that are quietly lying to you.
FAQs (Frequently Asked Questions)
Why do cash flow problems persist even when sales seem strong and the team is busy?
Cash flow issues often stem not from sales or obvious expenses, but from inventory accounting mistakes. Inventory can distort profits, hide theft or purchasing errors, and make certain product lines appear profitable while actually draining cash.
What common inventory accounting mistakes can kill cash flow?
Key mistakes include not tying inventory movement to actual purchases and sales, mixing cash basis thinking with accrual inventory accounting, ignoring landed costs like freight and duties, skipping regular cycle counts, and using incorrect or inconsistent inventory valuation methods.
How does not linking inventory movements to real purchasing and selling affect my business?
If your system shows inventory changes without connecting them to actual purchases and sales, you risk ‘phantom inventory’ and distorted financials. This can lead to poor reorder timing and unexpected cash shortages due to inaccurate profit representation.
Why is mixing cash basis thinking with accrual inventory accounting problematic?
Inventory is an asset until sold, so treating purchases as immediate expenses (cash basis) misrepresents profit. This leads to poor decisions like overstocking or cutting marketing based on misleading margin data, ultimately draining cash.
What is landed cost and why should I track it accurately?
Landed cost includes all costs to get inventory ready for sale—vendor price plus freight, duties, fees, etc. Ignoring these inflates profit margins falsely, causing underpricing and unprofitable sales that increase revenue but reduce cash flow.
How can regular cycle counts improve my cash flow management?
Cycle counts prevent inventory guesswork by identifying shrinkage from damage, theft, errors, or spoilage early. Consistent counting helps avoid overbuying (tying up cash) or stockouts (lost sales), both of which harm cash flow.