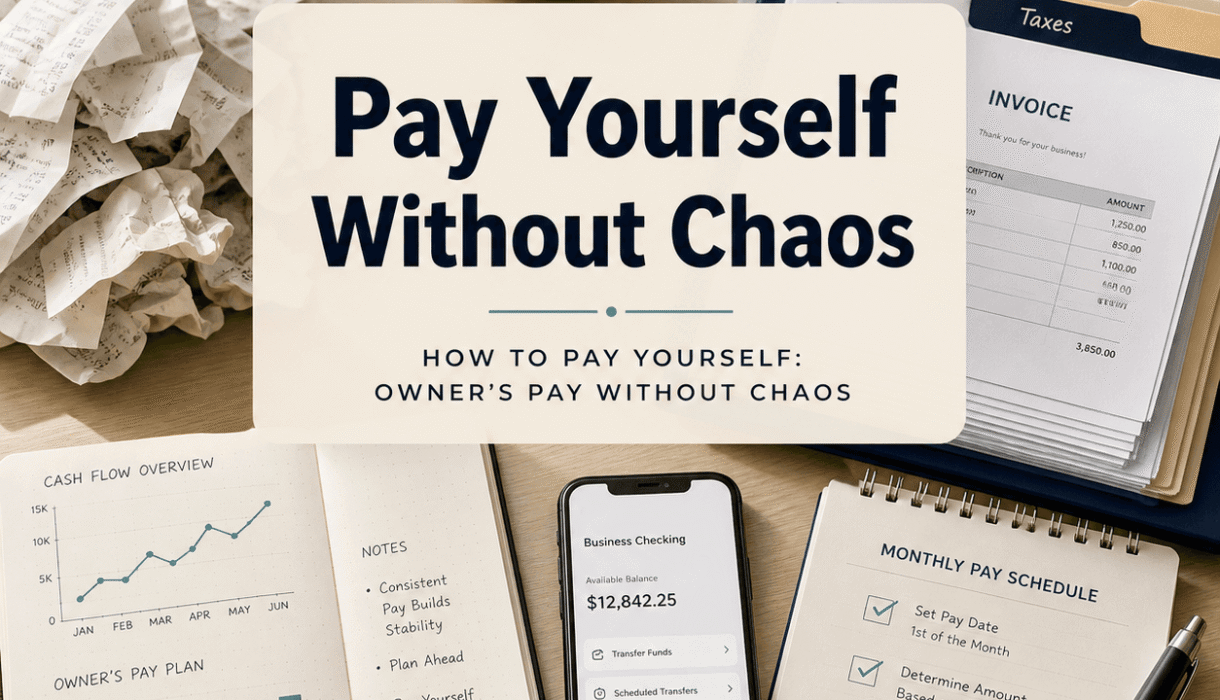

Paying yourself should be the easiest line item in your business.
And yet somehow it turns into this weird monthly stress ritual where you stare at the bank balance, do a couple mental calculations, then either overpay yourself and regret it later. Or underpay yourself and quietly resent your own company. Been there.
The tricky part is that owner’s pay is not just a money decision. It’s a systems decision.
When it’s messy, everything feels messy. Taxes feel scary. Cash flow feels random. You stop trusting your numbers. Then you start making “gut” decisions, which is basically just anxiety with confidence.
So let’s fix it. In a way that’s boring, repeatable, and does not depend on you being in a good mood on the 1st of the month.
The real goal: pay yourself like it’s normal
You’re not trying to “take money out.” You’re trying to create a pay structure that:
- Keeps your personal life stable
- Keeps the business funded
- Keeps taxes predictable
- Keeps your books clean enough that the numbers actually mean something
Owner’s pay gets chaotic for one simple reason. Most businesses try to pay the owner last, after everything else.
That sounds responsible, but in practice it often leads to randomness. You’re always last, which means you’re always improvising.
A healthier mindset is: owner’s pay is a planned expense. Not an afterthought.
To achieve this mindset, it’s crucial to effectively manage your business and establish systems that streamline financial decisions, making them less stressful and more predictable.
Step 1: First, figure out what kind of “owner” you are (legally)
Before we talk tactics, you have to know how your business is taxed, because it changes what “paying yourself” even means.
Here are the common setups:
Sole proprietor (or single member LLC taxed as sole prop)
You don’t pay yourself payroll wages. You take owner draws. It’s basically transfers from business to personal.
- No W-2 wages
- No payroll tax filings for your pay
- Your profit is still taxable to you personally, even if you don’t draw it
Partnership or multi member LLC
Similar concept. Owners typically take draws/distributions based on the agreement.
S corporation
This one is different. If you’re an owner who works in the business, the IRS expects you to pay yourself a reasonable salary via payroll.
That means:
- W-2 wages
- Payroll taxes
- Regular payroll filings
- Then you can also take distributions, depending on profit and cash flow
C corporation
You’re generally paid as an employee, often with wages and possibly dividends. Less common for small service businesses, but it exists.
If you are not sure what you are, stop and confirm it. Seriously. Most pay chaos starts right there.
If you want a second set of eyes on how things are set up in QuickBooks and whether your owner pay is being recorded correctly, Smart Bookkeeping Partner offers a free QuickBooks health check here: https://smartbookkeepingpartner.com/. That alone can clear up a lot of fog.
Step 2: Stop using your bank balance as a pay calculator
The bank balance is not your profit.
It’s not even your “available money,” not really. It’s just cash sitting there, and it might already be spoken for.
Your bank balance includes money needed for:
- Payroll for your team
- Upcoming vendor bills
- Sales tax
- Debt payments
- Quarterly taxes
- Reimbursements
- Subscriptions you forgot existed
- The next slow week that always shows up
So if your current method is “if there’s $18,000 in checking, I can probably take $6,000,” that’s chaos. It just wears a nicer outfit.
What you want instead is a pay method based on:
- Historical averages
- A cash buffer
- A predictable schedule
- Simple rules you can follow even when you’re busy
To better understand your financial situation, consider conducting a survey to gain insights into your cash flow and expenses. This data will help you make informed decisions about your pay method.
Step 3: Pick a pay method that matches your business reality
There are a few clean ways to do owner pay. The best one depends on how stable your revenue is and how mature your bookkeeping is.
Here are the most practical options.
Option A: Fixed owner pay (best for stability)
You pay yourself a set amount on a set schedule. Every two weeks. Or twice a month. Or monthly.
This works best when:
- Revenue is fairly consistent
- You want personal predictability
- You’re building discipline into the business
How to set it:
- Look at the last 6 to 12 months average monthly net income (not gross revenue)
- Decide what portion can safely be paid out while still leaving the business with oxygen
- Start slightly conservative for the first 60 to 90 days
- Adjust quarterly, not weekly
This alone eliminates most of the “can I afford it” spiral.
Consider analyzing your cash flows to determine the best fixed amount to draw as owner pay without jeopardizing the business’s financial health.
Option B: Base pay + profit distributions (best for growing businesses)
This is the combo a lot of owners end up loving.
- You take a smaller fixed amount consistently (base pay)
- Then you take a distribution monthly or quarterly if the business hits profit and cash targets
This works best when:
- Your revenue swings month to month
- Your expenses are predictable enough
- You want upside without wrecking cash flow
The key is to define what “profit” means in your system. Not vibes.
Option C: Percentage based draws (best for variable revenue, early stage)
You draw a fixed percentage of collected revenue. Keyword is collected.
Example: draw 10% of revenue that hits the bank each week.
This works when you’re early and trying to keep it simple, but you need rules, like:
- Only draw after taxes are set aside
- Only draw from operating surplus, not from money reserved for bills
- Reconcile regularly so your percentage isn’t based on fantasy
This option can get messy if bookkeeping lags behind, because you might overpay yourself based on revenue that later gets eaten by expenses you didn’t account for.
Step 4: Build the “owner pay stack” (this is where it gets calm)
Here’s the simplest system I’ve seen actually work long term. It’s not fancy. It’s just organized.
Think in layers, like priorities.
Layer 1: Operating account is for operations
This is where revenue lands and bills get paid. It should not be the account you randomly siphon from when you feel like it. It’s essential to have a clear operating agreement in place to define how this account functions and ensure smooth operations.
Layer 2: Owner pay account
This is where your pay comes from. Even if you’re a sole proprietor and it’s technically “draws,” you can still run it like payroll.
The point is separation.
Layer 3: Tax reserve account
This is the account that keeps you from hating April.
You regularly move money here. Monthly at minimum. Some businesses do weekly.
Layer 4: Savings or buffer account (optional but powerful)
This is your future calm. Equipment replacement. Slow season cushion. Opportunity fund.

Now the magic is not the accounts themselves.
The magic is the habit: money flows through a process, not through your emotions.
Step 5: Choose a schedule and stop renegotiating it every month
Owner’s pay works when it’s boring.
Pick one:
- Every Friday
- Every other Friday
- 1st and 15th
- Once a month
And then commit to it for at least one full quarter.
The problem with inconsistent pay isn’t just lifestyle. It messes up your ability to see patterns.
If you pay yourself randomly, then:
- Your P&L becomes harder to interpret
- Cash flow looks “lumpy”
- You don’t know what the business can sustain
- You can’t forecast without guessing
So pick a schedule that matches your revenue cycle.
If most customers pay you mid month, don’t schedule owner pay on the 2nd. You’re just setting yourself up to panic.
Step 6: How much should you pay yourself, actually?
This is the part everyone asks, and the honest answer is… it depends.
But we can still make it concrete.
If you’re a sole proprietor or partnership
You’re paying yourself out of profit, but profit and cash are not always aligned.
A good starting approach:
- Decide what you need personally as a baseline
- Then validate the business can support it consistently
- Keep a buffer and tax reserves before increasing draws
If you can’t cover your personal baseline without draining the business, that’s a pricing, expense, or volume problem. Not a “pay yourself” problem.
If you’re an S corp
You need a reasonable salary if you work in the business.
Reasonable usually means:
- What you would pay someone else to do your job
- Based on market rates, responsibilities, time spent, and profitability
Then distributions come after, based on profit and cash.
The big mistake with S corps is skipping payroll or paying an unrealistically low wage and trying to take everything as distributions. That can trigger IRS attention, and even if it doesn’t, it’s still risky.
If you’re not sure whether your current setup is clean, this is the kind of thing Smart Bookkeeping Partner helps owners untangle through bookkeeping + payroll support and advisory. The goal is not just “compliance,” it’s clarity. You can start here: https://smartbookkeepingpartner.com/ or call 985-401-1210.
Step 7: Record owner’s pay correctly (so your reports stop lying)
This is a big one. Because a lot of owners think they’re unprofitable when they’re not, or profitable when they’re not, because owner pay is coded wrong.
Here’s the general guidance:
Sole proprietor
- Owner draws should not hit the P&L as an expense
- They should be recorded to an equity account like “Owner’s Draw” or “Owner’s Equity”
If you code draws as “Wages” or “Contract Labor,” your profit will look lower than it really is. Then you start making bad decisions. Like raising prices when you didn’t need to. Or cutting expenses that were fine.
S corp
- W-2 wages should be recorded as wage expense (on the P&L)
- Owner distributions should be recorded to equity, not wages
Mixing these up makes your financials confusing, and it can cause payroll reporting issues too.
Reimbursements (quick note)
If you pay for business expenses personally, reimbursements should be tracked cleanly. Not shoved into owner draws as a catch all. You want to know what the business actually costs to run.
If your QuickBooks file is currently a mix of draws, reimbursements, personal Amazon purchases, and mystery transfers, you are not alone. But it does need cleanup, because you cannot build a sane owner pay system on top of messy books.
Step 8: Create two rules that prevent the “oops I overpaid myself” problem
Here are two rules I like because they’re simple and they work.
Rule 1: You only increase owner pay quarterly
Not monthly. Not because you had a great week. Quarterly.
Why? Because one good month can be an illusion. Seasonality. A big one time project. Delayed expenses.
Quarterly gives you enough time to see reality.
Rule 2: Owner pay comes from free cash, not hopeful cash
Free cash means:
- Bills due before next revenue cycle are covered
- Taxes are set aside
- Minimum cash buffer is intact
If you don’t have a cash buffer target, set one.
A common starting point is one month of core operating expenses. Some businesses go for two. Three if the industry is volatile.
Step 9: The simplest owner pay workflow (steal this)
Here’s a straightforward monthly workflow that doesn’t take forever.
Weekly (15 minutes)
- Check bank balances
- Move a set percentage to tax reserve (or a fixed amount)
- If you do percentage draws, calculate based on collected revenue
Monthly (30 to 60 minutes)
- Reconcile bank and credit cards
- Review P&L and balance sheet
- Confirm tax reserve is on track
- Transfer owner pay to personal per schedule
Quarterly (60 to 90 minutes)
- Review last quarter profit trend
- Adjust owner pay up or down
- Plan for quarterly estimated taxes
- Refresh cash flow forecast for next quarter
If you can’t do the review because your books aren’t reconciled, that’s the bottleneck. Every time.
Clean books first. Then owner pay becomes easy.

Understanding how to manage your finances effectively can also be beneficial when dealing with retail lending situations. For more detailed insights, refer to this comprehensive guide on retail lending.
Step 10: What “chaos” usually looks like (so you can spot it fast)
A few red flags that owner pay is off the rails:
- You avoid looking at financial reports because they stress you out
- You take draws, then put personal money back in later to cover bills
- Your tax bill surprises you every year
- You don’t know if you’re actually profitable, you just feel busy
- Your accountant asks questions you cannot answer, like “what is this transfer”
- Your books are always a month or two behind
This is fixable. It just needs a system, and maybe a little help cleaning up the foundation.
A quick note on getting help (because sometimes you’re too close to it)
If you’re reading this and thinking, “Yes, but my QuickBooks is a mess, and I don’t trust any of the numbers,” then owner pay is not the first thing. Bookkeeping is.
That’s basically the whole positioning of Smart Bookkeeping Partner. Clean reconciled books first, then decision ready data. Then CFO style support like cash flow monitoring, forecasting, KPI tracking, profitability analysis. The stuff that makes paying yourself feel obvious instead of dramatic.
If you want a low pressure starting point, their free QuickBooks health check is a good move: https://smartbookkeepingpartner.com/
Or call 985-401-1210 if you prefer talking it through.
Let’s wrap this up (and make it real)
Owner’s pay without chaos is not about finding the perfect number. It’s about removing randomness.
Here’s the simple path:
- Know your entity type and what “paying yourself” legally means
- Stop using the bank balance as your decision tool
- Pick a method: fixed pay, base + distributions, or percentage draws
- Separate accounts so money flows with intention
- Set a schedule and stick to it for a full quarter
- Record it correctly so your reports tell the truth
- Build two guardrails: quarterly changes only, and pay from free cash
That’s it. Not glamorous, but it works.
And when it works, you start trusting your business again. Which is kind of the whole point.
FAQs (Frequently Asked Questions)
Why does paying myself as a business owner often feel stressful and chaotic?
Paying yourself can feel stressful because it often becomes an afterthought, with owners improvising based on the bank balance rather than a planned system. This leads to uncertainty around cash flow, taxes, and trust in your financial numbers, turning what should be a simple process into a monthly anxiety ritual.
What is the recommended mindset for owner’s pay to avoid financial chaos?
The healthier mindset is to treat owner’s pay as a planned expense, not an afterthought. This means creating a consistent pay structure that keeps your personal life stable, funds the business properly, makes taxes predictable, and maintains clean books so your financial data remains meaningful.
How does the legal structure of my business affect how I should pay myself?
Your business’s legal and tax structure determines your method of paying yourself. For example, sole proprietors take owner draws without payroll wages; partnerships do similar draws based on agreements; S corporations require paying yourself a reasonable salary with payroll taxes plus possible distributions; and C corporations typically pay wages and dividends. Knowing your structure is crucial to managing owner pay correctly.
Why shouldn’t I use my bank balance to decide how much to pay myself?
Your bank balance isn’t an accurate reflection of available funds because it includes money allocated for payroll, bills, taxes, debt payments, subscriptions, and other obligations. Using it as a pay calculator can lead to random or risky decisions. Instead, base your pay on historical averages, maintain a cash buffer, follow a predictable schedule, and use simple rules.
What are some effective methods for determining owner’s pay?
One practical method is fixed owner pay—paying yourself a set amount on a consistent schedule (e.g., monthly or biweekly). This works best when revenue is stable and you want personal predictability. To set this up: analyze 6-12 months of average net income, decide what portion can safely be paid out while keeping the business healthy, start conservatively for 60-90 days, and adjust quarterly rather than weekly.
How can I ensure my bookkeeping supports clear and stress-free owner’s pay decisions?
Maintaining clean books with accurate records helps your numbers mean something and reduces stress around owner’s pay. Consider getting a QuickBooks health check or professional bookkeeping support to confirm your setup is correct. Proper bookkeeping clarifies profits versus cash flow and helps you plan consistent owner compensation systems.