
If you have ever said something like…
“I’m profitable but I’m broke.”
…yeah. Same. I mean, not me personally. But I’ve heard it so many times from business owners it might as well be a slogan.
And it usually happens for one simple reason: your P and L is not your bank account. Profit is a story about performance. Cash is the story about survival.
A cash flow forecast is the bridge. Not a fancy one. Not the kind you need an MBA to build.
Just a simple, real world template you can update in 10 minutes and actually use to make decisions. Payroll. Inventory. Taxes. That big equipment purchase you keep putting off. The next hire. Whether you should run that promo. Whether you should chill for two weeks and let cash stack.
That’s what this is.
So I’m going to show you the cash flow forecast template owners actually use. The one we use in advisory work. The one that doesn’t turn into a dead spreadsheet after three weeks.
And yes, I’ll include the layout, formulas, and how to run it even if your books are a little messy right now.
Why most cash flow templates fail (even if they look “professional”)
Most templates fail because they do one of these:
- They confuse cash flow with profit.
They start with revenue and expenses like a P and L and call it a forecast. That’s not cash flow. - They are built for accountants, not owners.
Too many categories, too many tabs, too many assumptions. You stop trusting it. Then you stop using it. - They ignore timing.
Timing is literally the whole game. When money hits the bank. When it leaves. Not when you “earned” it. - They don’t match how your business actually operates.
If you run projects, your cash comes in chunks. If you’re subscription based, it’s smoother. If you do product, you have inventory spikes. Templates that pretend every business is the same just don’t stick.
So we’re going to build the one that sticks.
The template (high level): what you’re building
This is the structure:
- A weekly forecast for the next 13 weeks (yes, weekly, not monthly)
- Built around your actual bank balance
- With cash in and cash out that reflect timing
- And a clear ending cash balance each week
Why 13 weeks?
Because it’s long enough to see problems coming, short enough to be realistic. Owners can forecast 13 weeks without turning it into fantasyland.
If you only do monthly forecasting, you will miss the week where payroll hits on Friday and sales deposits don’t land until Tuesday. That is how surprises happen.
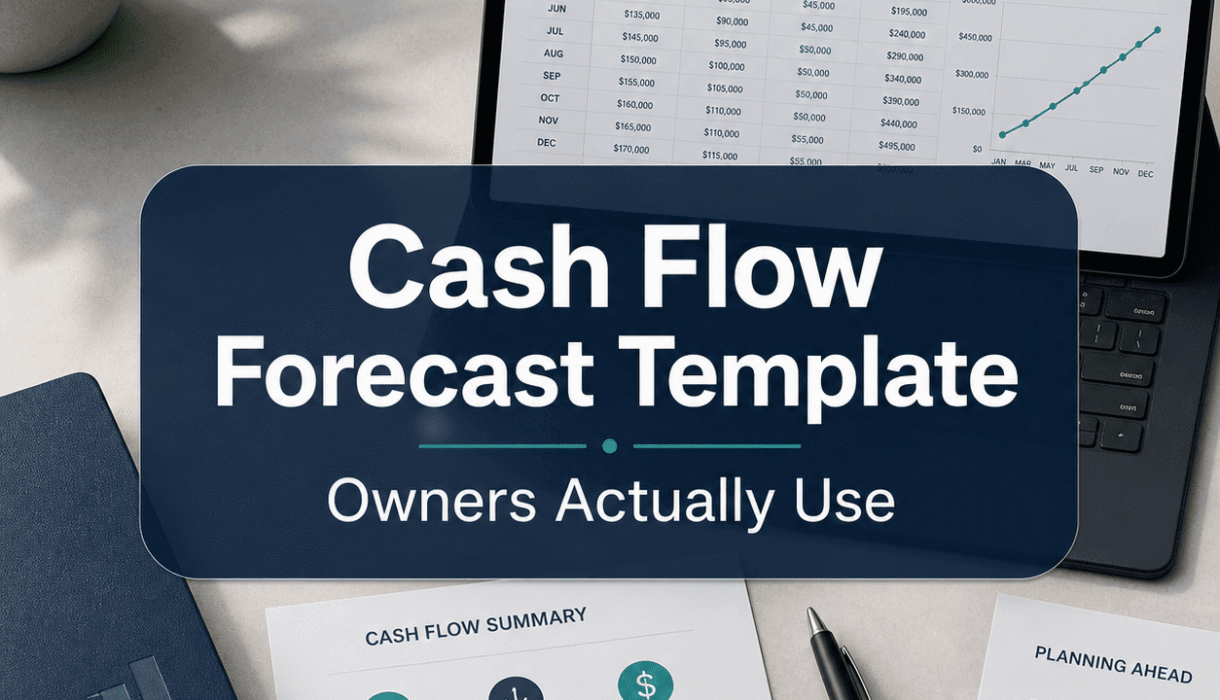
Insert image: simple 13 week cash flow forecast screenshot
Alt text: 13-week cash flow forecast template showing beginning cash, cash in, cash out, and ending cash by week.
(If you’re publishing this on WordPress and you don’t have this image yet, just replace the URL with your actual media upload. The visual helps a lot.)
The cash flow forecast template owners actually use (columns and rows)
Open Excel or Google Sheets and create the following columns:
- Column A: Category
- Column B: Notes / Assumptions (optional, but you’ll love this later)
- Columns C onward: Week 1 through Week 13, each labeled by date range (for example:
Oct 7 to Oct 13)
Now rows.
Section 1: Beginning Cash
- Row: Beginning Cash (Bank Balance)
This is the only place you start. Not with sales. Not with profit.
Beginning Cash = what’s in the bank at the start of that week.
If you have multiple bank accounts, you can:
- combine them into one number (simpler), or
- list each account and subtotal (more detailed)
Section 2: Cash In (inflows)
Keep this simple. The goal is accuracy, not perfect categorization.
Typical inflow rows:
- Customer Collections (AR)
- Cash Sales / Daily Deposits
- Owner Contributions
- Loan Proceeds
- Other Income (refunds, rebates, etc.)
If you’re service based and invoice clients, most of your inflow belongs in Customer Collections.
If you’re retail or ecom, you’ll use Cash Sales and you may need to account for processor timing (Stripe, Shopify, Square). Money might land 2 to 4 days later.
Section 3: Cash Out (outflows)
Again, keep it usable.
Typical outflow rows:
- Payroll (net pay)
- Payroll Taxes / Benefits
- Rent
- Utilities
- Software / Subscriptions
- Insurance
- Materials / Inventory Purchases
- Contractors
- Loan Payments
- Credit Card Payments
- Sales Tax / Payroll Tax Deposits
- Income Tax Estimates
- Owner Draws
- Other
Yes, “Other” is allowed. You’re not failing because you used “Other”. You’re winning because you kept it alive.
Section 4: Totals + Ending Cash
Add these rows:
- Total Cash In
- Total Cash Out
- Net Cash Flow (In minus Out)
- Ending Cash
Then:
- Next week’s Beginning Cash should equal last week’s Ending Cash.
That one link is what turns this from a list into a forecast.
Insert image: layout close up
Alt text: Close-up of cash flow forecast showing cash in and cash out categories by week.
The formulas (simple and dependable)
Let’s say:
- Beginning Cash is in row 2
- Total Cash In is in row 12
- Total Cash Out is in row 25
- Ending Cash is in row 28
- Week 1 is column C, Week 2 is column D, etc.
Total Cash In
In Week 1 cell:
=SUM(C5:C10) (adjust for your inflow rows)
Total Cash Out
=SUM(C15:C23) (adjust for your outflow rows)
Net Cash Flow
=C12 - C25
Ending Cash
=C2 + C27
(or =C2 + C12 - C25)
Beginning Cash for Week 2
In the Week 2 Beginning Cash cell:
=C28
Then drag across for all weeks.
That’s it. That is the engine.
The part most owners miss: your forecast is a collections schedule, not a sales goal
This is where templates get real.
You do not forecast “sales”. You forecast cash receipts.
So instead of asking, “How much will we sell next month?”
Ask:
- Which invoices will actually get paid in Week 3?
- How much is already in AR?
- What is the likely lag time for each client?
- What autopays are coming in?
- What is the realistic collection amount, not the hopeful one?
Quick method (good enough and surprisingly accurate)
For Customer Collections, use:
- Collections from existing AR (what’s already invoiced)
- Collections from new invoices (what you expect to bill and collect within 13 weeks)
If you’re in QuickBooks, pull:
- Open Invoices report (AR aging)
- Sales by Customer Summary
- Deposit detail from the last 8 to 12 weeks (this is the truth serum)
If you don’t have clean books, do not panic. You can still forecast, you just have to use bank history as the starting point. Then improve the books as you go.
How to fill this out in 30 minutes (first version)
This is the workflow we use because it keeps things moving.
Step 1: Put in your real beginning cash
Log into your bank. Enter the balance.
If today is mid week, pick a consistent “week start” (Monday is common) and use the closest bank balance.
Step 2: Lock in the big fixed outflows first
Enter what you already know:
- Payroll dates and amounts
- Rent
- Loan payments
- Subscription bundles
- Insurance
These are not guesses. They are scheduled.
Step 3: Add the “lumpy” items
These are the ones that blow up weeks:
- Sales tax payments
- Annual renewals
- Quarterly taxes
- Inventory buys
- Equipment deposits
- Big contractor payments
Put them on the exact week they will clear the bank, not the week you “incur” them.
Step 4: Forecast cash in with a conservative bias
Add expected receipts by week.
If you’re not sure, start with:
- average weekly deposits from the last 8 weeks
- then adjust for anything you know is changing (seasonality, new contract, lost client)
Step 5: Add a buffer line (optional but smart)
Create a row under cash out called:
- Buffer / Unknowns
Put a small number there weekly if your business is messy. Even $200 to $500 a week. This stops the forecast from lying to you.
Insert image: weekly update checklist
Alt text: Checklist showing steps to update a cash flow forecast weekly.
How owners actually use this (decisions, not reporting)
A cash flow forecast is not a report you admire. It’s a tool you argue with a little. You adjust it. You use it to answer questions like:
1. Can we make payroll comfortably?
Not “can we technically make it”. Comfortably.
If the forecast shows you dropping to $2,000 after payroll and your normal weekly outflow is $18,000… you’re not comfortable. You’re exposed.
2. When should we pay the credit card?
A lot of businesses pay the credit card when it feels urgent, not when it’s optimal.
With a forecast, you can time it:
- pay earlier when you have surplus
- pay minimum when a cash crunch week is coming
- plan a larger payment right after a known deposit week
3. Should we buy inventory now or next week?
One week can matter. Especially if you’re floating vendor bills.
4. Can we afford to hire?
You don’t decide hiring off one “good month”.
You decide it off whether the next 13 weeks can absorb:
- wages
- taxes
- benefits
- ramp time
A forecast shows that.
5. Are we actually ready for growth?
Sometimes growth is the cash problem. Not the solution.
More sales can mean:
- more labor before you collect
- more materials upfront
- bigger tax payments later
A forecast makes that visible.
The 3 levels of this template (pick your reality)
Not every business needs the same complexity. Here are the three versions we see owners stick with.
Level 1: The “I just need to sleep” forecast
- Total cash in per week (one line)
- Total cash out per week (one line)
- Payroll shown separately
- Ending cash
This is surprisingly powerful. And yes, it counts.
Level 2: The “I’m running a real operation” forecast
- Cash in split by: collections, cash sales, other
- Cash out split by: payroll, rent, inventory/materials, debt, taxes, other
This is the sweet spot for most businesses.
Level 3: The “we are scaling and need control” forecast
- Cash in by customer or channel
- Cash out by vendor group
- Separate tab for AR schedule
- Separate tab for AP schedule
- Scenario planning (base, conservative, aggressive)
This is where CFO advisory support becomes worth it because you can overbuild it fast.
Common mistakes (the ones that quietly wreck forecasts)
Mistake 1: Forgetting timing on merchant processing
If you run cards, your sales might happen Friday and cash lands Tuesday. Or later on holidays.
Fix: build a “processor lag” assumption, even if it’s rough.
Mistake 2: Treating loan payments as one line expense
Loan payments have principal and interest, but for cash flow you mostly care about the cash leaving.
Fix: forecast the actual payment amount and date.
Mistake 3: Ignoring tax season until it’s a crisis
Taxes are predictable. The pain comes from not putting them on the calendar.
Fix: put placeholder estimates in the weeks you expect to pay, then refine later.
Mistake 4: Using a forecast without reconciled books
You can start without perfect books, but eventually the template drifts if your numbers are not grounded.
If you are not reconciling monthly, your starting cash might be right but your assumptions about payables, receivables, and true burn rate will be off.
This is where clean bookkeeping stops being a nice to have and becomes the foundation.
QuickBooks note: garbage in, garbage out (but we can fix it)
If your QuickBooks file has:
- unreconciled bank accounts
- random “Ask My Accountant” piles
- negative AR that makes no sense
- old bills sitting there forever
- payroll coded weirdly
…your forecast will feel cursed.
Not because forecasting is hard. Because the underlying data is not decision ready yet.
If you want a fast reality check, Smart Bookkeeping Partner offers a free QuickBooks health check where you get a walkthrough of what’s clean, what’s not, and what that means for cash flow and reporting.
You can find that at https://smartbookkeepingpartner.com/ or call 985-401-1210 if you’d rather just talk it through.
Subtle pitch, yes. But honestly, this is exactly the kind of thing that makes forecasting finally click for owners.
The weekly routine (how this stays alive)
Here’s the routine we recommend. It’s boring. It works.
Every week (10 to 15 minutes)
- Update beginning cash (or confirm it matches the bank).
- Replace last week’s forecasted numbers with actuals.
- Push or pull expected receipts based on real conversations and invoice statuses.
- Adjust any one time expenses that moved.
- Scan the lowest ending cash week. Ask: “What would I do if that week was next week?”
That’s the whole discipline.
You don’t need perfect. You need current.
Insert image: example of actual vs forecast swap
Alt text: Cash flow forecast showing prior week replaced with actual cash in and cash out amounts.
A simple example (what this looks like in real life)
Let’s say it’s Week 1 and you have $48,000 in the bank.
You enter outflows:
- Payroll: $22,000 (Week 2)
- Rent: $4,800 (Week 1)
- Vendor payment: $9,000 (Week 3)
- Sales tax: $6,500 (Week 4)
Inflows:
- Client A pays $18,000 (Week 2)
- Client B pays $7,500 (Week 3)
- Average weekly deposits: $12,000 otherwise
You build it out and notice Week 4 ending cash drops to $3,200.
Now you have choices:
- move the $9,000 vendor payment to Week 5
- collect partial payment earlier from Client B
- pause owner draws for 2 weeks
- delay a non essential subscription annual renewal
- run a quick AR push with incentives
That’s the value. Not the spreadsheet.
The spreadsheet just forces the conversation early, when you still have options.
Want the template?
If you want, you can copy this layout directly into Google Sheets or Excel. It’s intentionally plain.
And if you want someone to sanity check it against your actual QuickBooks setup, cash cycles, payroll schedule, and tax obligations, that’s literally what Smart Bookkeeping Partner does in its bookkeeping and CFO advisory work.
Start here: https://smartbookkeepingpartner.com/
Or call: 985-401-1210
Additionally, understanding the implications of these financial decisions is crucial. For instance, the psychological aspects of budgeting and financial decision-making can significantly impact your business’s financial health.
Wrap up (what to do next)
If you do nothing else, do this:
- Build a 13 week forecast.
- Start with your real bank balance.
- Forecast receipts by when cash hits, not when you “earn” revenue.
- Put payroll, taxes, and other lumpy stuff on the exact weeks.
- Update weekly. Keep it alive.
That’s the cash flow forecast template owners actually use.
Not because it’s pretty. Because it tells the truth early enough to do something about it.
FAQs (Frequently Asked Questions)
Why do many business owners say ‘I’m profitable but I’m broke’ and how does cash flow forecasting help?
Many business owners experience being profitable on paper but lacking cash in the bank because profit (P&L) reflects performance, not actual cash availability. Cash flow forecasting bridges this gap by tracking when money actually enters and leaves your bank account, helping you manage survival by planning for real-world cash timing.
What are common reasons most cash flow templates fail for business owners?
Most cash flow templates fail because they confuse cash flow with profit, are overly complex and built for accountants rather than owners, ignore the timing of cash movements, and don’t align with how different businesses operate (like project-based vs subscription vs product inventory). These issues cause owners to lose trust and stop using them.
What is the structure of an effective cash flow forecast template that business owners can use?
An effective template features a weekly forecast for 13 weeks based on your actual bank balance, detailing cash inflows and outflows with accurate timing, and showing a clear ending cash balance each week. This timeframe is realistic enough to anticipate problems without becoming speculative.
How should I set up the columns and rows in my 13-week cash flow forecast spreadsheet?
Create columns starting with Category (Column A), Notes/Assumptions (Column B), then Week 1 through Week 13 labeled by date range across subsequent columns. Rows should include Beginning Cash (your actual bank balance), sections for Cash In (like Customer Collections, Cash Sales), Cash Out (such as Payroll, Rent, Inventory Purchases), followed by totals: Total Cash In, Total Cash Out, Net Cash Flow, and Ending Cash which feeds into next week’s Beginning Cash.
What are typical categories to include under Cash In and Cash Out in a practical cash flow forecast?
For Cash In: Customer Collections (accounts receivable), Cash Sales/Daily Deposits, Owner Contributions, Loan Proceeds, Other Income like refunds or rebates. For Cash Out: Payroll (net pay), Payroll Taxes/Benefits, Rent, Utilities, Software Subscriptions, Insurance, Materials/Inventory Purchases, Contractors, Loan Payments, Credit Card Payments, Tax Deposits, Owner Draws, plus an ‘Other’ category to capture miscellaneous expenses.
Why is it important to forecast cash flow weekly rather than monthly?
Weekly forecasting captures the precise timing of money entering and leaving your bank account—like payroll hitting on Friday but sales deposits arriving Tuesday—which monthly forecasts can miss. This detailed timing helps prevent surprises that threaten business survival by ensuring you always know your true cash position week-to-week.